The First National Bank & Trust Co. is now Brooks Bank. New name, same people, same community banking you trust. Learn More

Mortgage Loan Lenders Serving Oklahoma City and Surrounding Areas

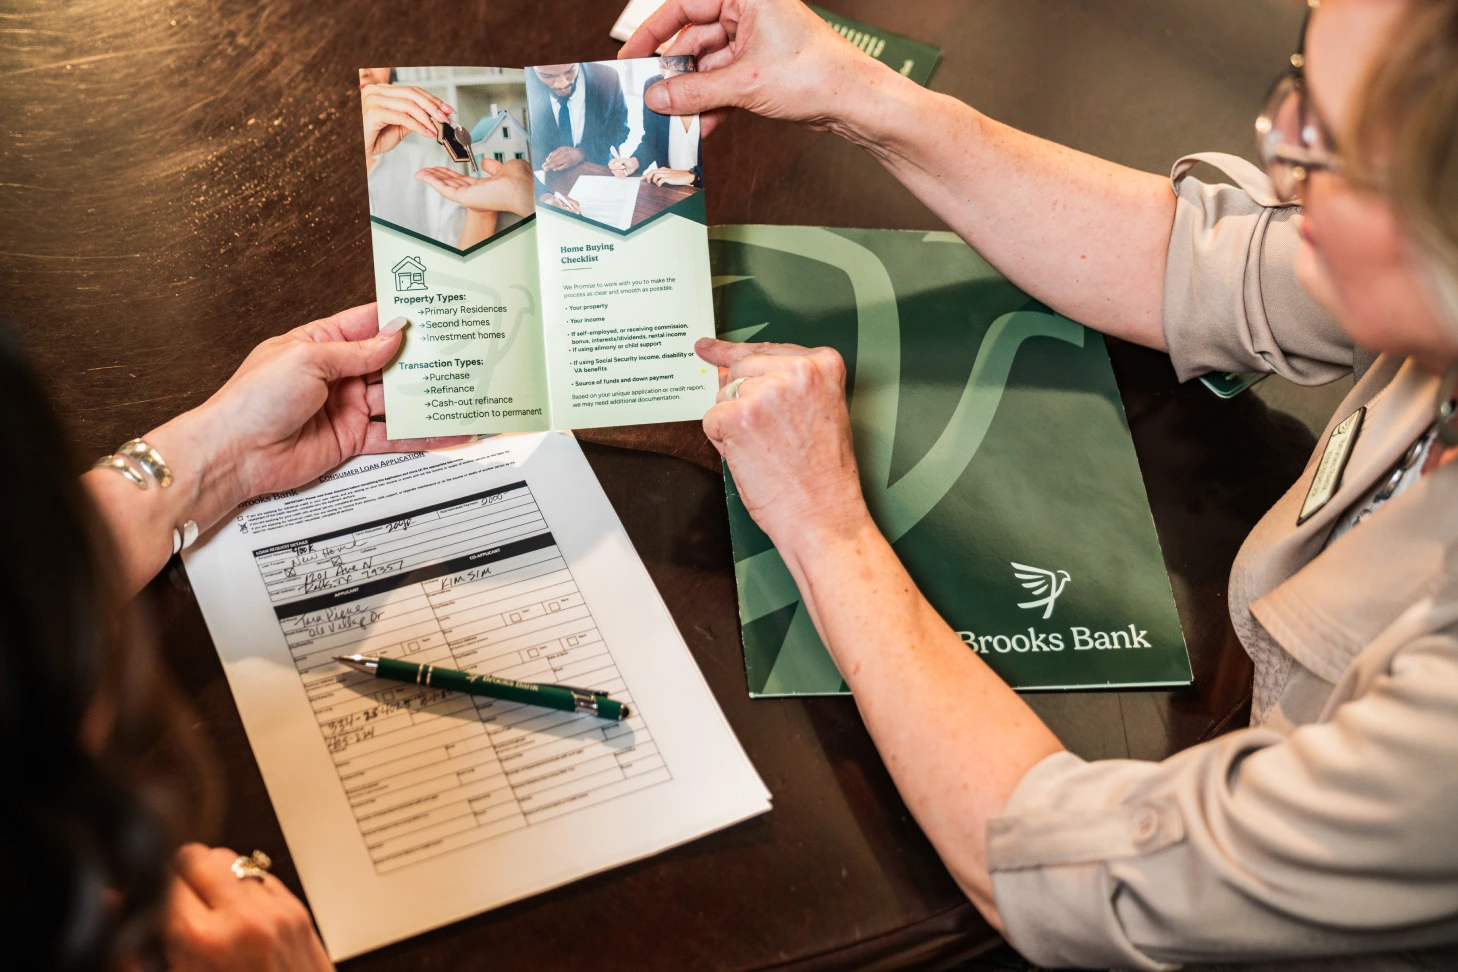
From your first home to your forever home, Brooks Bank mortgage loan lenders offer local decisions, local servicing, and the personal guidance to help you close with confidence.

Mortgage Loan Services

Real Mortgage Solutions

Brooks Bank has offered mortgage loan services since 2000, and today our local home mortgage lenders provide the full range of home loan options for buyers and homeowners in Oklahoma City, Newcastle, Blanchard, Goldsby, and surrounding areas. When you finance your home with Brooks Bank, you work directly with a local team that knows our community. We are here to guide you through every step of the origination process, answer your questions, and help you find the right loan for your future. NMLS #403159.

*subject to credit approval and/or subject to additional terms and conditions.
Our Loan Types

Explore the mortgage loan options available at Brooks Bank. Our mortgage lenders will help you find the right loan for your situation.

Local Fixed Rate Home Loans

Keep your mortgage local from origination to payoff. Fixed rates, local servicing, and lenders who live where you live.

Conventional Fixed Rate Loans

Traditional fixed-rate mortgages with stable monthly payments for primary residences, second homes, and investment properties.

USDA Rural Development Loans

Zero down payment financing for eligible properties in designated rural areas of Oklahoma.

VA Loans

Mortgage financing for eligible veterans, active-duty service members, and qualifying surviving spouses.

FHA Loans

Low down payment mortgages insured by the Federal Housing Administration for qualifying borrowers.

Adjustable Rate Mortgage Loans

Initial rates that adjust over time. Ideal for buyers who plan to refinance or move within a defined period.

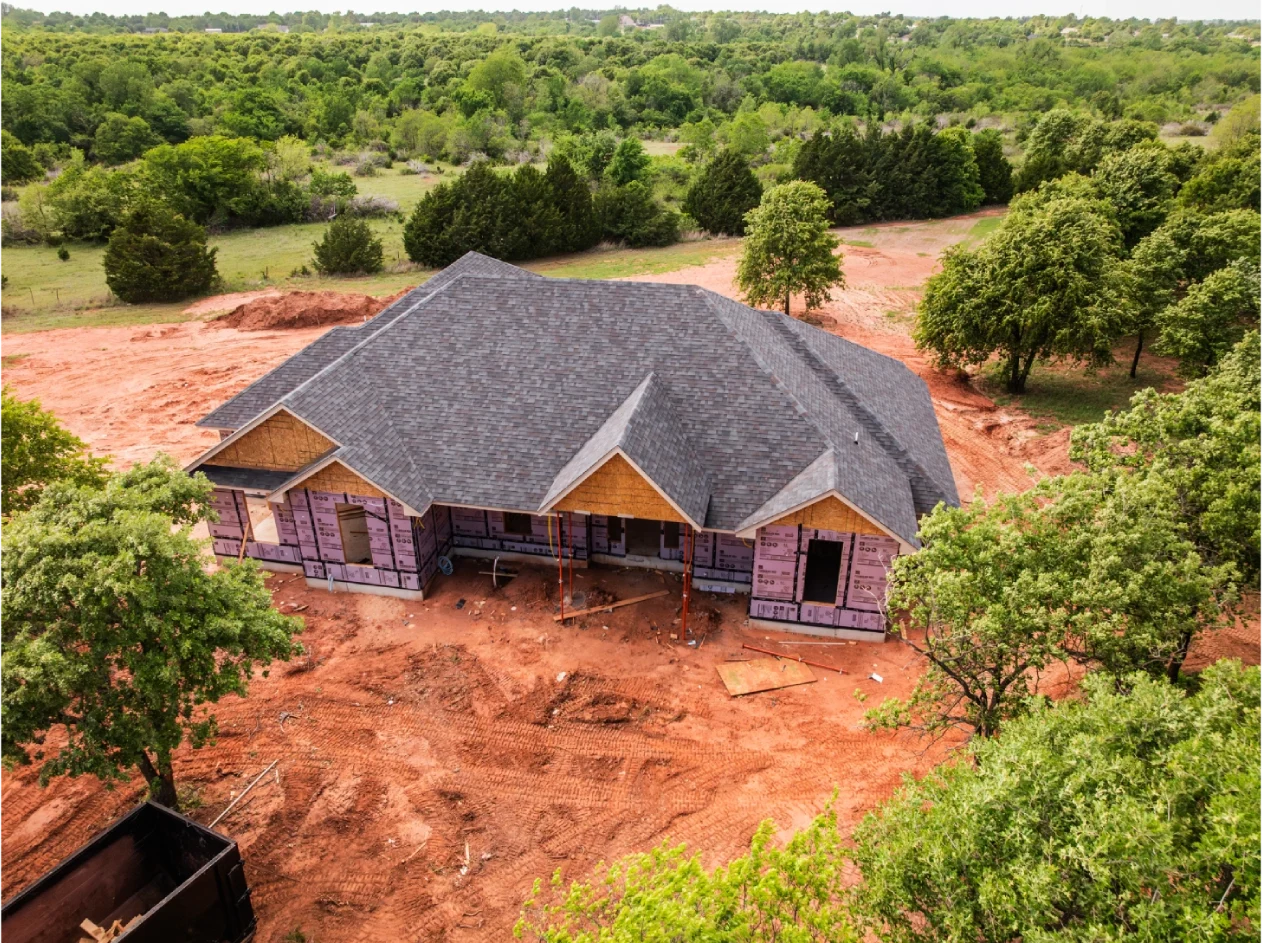
Home Construction Loans

Mortgage loans for new construction with draws during the building process then refinancing to a permanent mortgage.

Trusted Stories ‍in Motion

Faqs

Frequently Asked Questions

Can closing costs be financed?

On purchase transactions, closing costs generally cannot be financed into the loan. On a refinance, closing costs can be financed into the loan as long as loan-to-value limits are met. Your Brooks Bank mortgage lender can walk you through the specifics for your situation.

How much cash will I need to purchase a home?

The cash needed depends on several factors, but generally you will need earnest money (a deposit made when you submit your offer), a down payment (a percentage of the home's cost due at settlement), and closing costs (fees associated with processing the purchase paperwork). Down payment requirements vary by loan type.

How do I know how much house I can afford?

Generally speaking, you can purchase a home with a value of two to three times your annual household income. The amount you can borrow also depends on your employment history, credit history, current savings and debts, and the size of your down payment. Special loan programs for first-time buyers may allow you to purchase a home with a higher value. Contact a Brooks Bank mortgage lender at 405-224-2200 to determine exactly how much you can afford.

Does the bank offer OHFA or other down payment assistance programs?

Brooks Bank does not currently offer OHFA down payment assistance. From time to time, we have access to other down payment assistance programs, but availability varies. Contact a mortgage lender to discuss what may be available for your situation.

What are the current mortgage rates in Oklahoma today?

Mortgage rates change daily based on market conditions. Contact a Brooks Bank mortgage lender at 405-224-2200 for the most current rates on all loan types, or visit any location to discuss your options.

How do I get pre-qualified for a mortgage in Oklahoma?

Contact a Brooks Bank mortgage lender at 405-224-2200 or visit any of our Brooks Bank locations to start the pre-qualification process. You will need to provide income documentation, employment history, and consent for a credit check. Pre-qualification gives you a clear picture of what you can afford and strengthens your offer when you find the right home.

What is the difference between a fixed-rate loan and an adjustable-rate loan?

With a fixed-rate mortgage, the interest rate stays the same for the life of the loan, giving you stable and predictable monthly payments. With an adjustable-rate mortgage (ARM), the interest rate changes periodically based on a market index, which means your payments may go up or down over time. Each type has advantages depending on your situation. A Brooks Bank mortgage lender can help you determine which option is the best fit.

What does my credit score need to be?

Credit score requirements depend on the loan program. Generally, a score of 620 or above is required for most loan types. Some programs like FHA may allow lower scores with a larger down payment. Contact a Brooks Bank mortgage lender to discuss your specific credit situation.

Can I get pre-qualified for a loan?

Yes, and it is a smart step to take before shopping for a home. Most real estate agents want to see a pre-qualification letter before showing you properties. All you need is a completed application to get started. Apply for a mortgage loan by contacting a Brooks Bank mortgage lender at 405-224-2200 or through our online mortgage portal.

What does my mortgage payment include?

For most homeowners, the monthly mortgage payment includes three parts: principal (repayment of the amount borrowed), interest (the cost of borrowing), and an escrow payment for property taxes and homeowner's insurance. The escrow feature is sometimes optional, in which case you would pay taxes and insurance directly.

How long does the mortgage closing process typically take?

The timeline varies depending on the loan type, property, and complexity of the transaction. Our local lending team works to move efficiently and will keep you informed throughout the process. Contact a mortgage lender at 405-224-2200 to discuss your specific timeline.

How much of a down payment do I really need for a house?

It depends on the loan type. VA and USDA loans offer zero down payment options. FHA loans require as little as 3.5% down. Conventional loans can go as low as 3% down for qualifying borrowers. Our mortgage loan lenders can help you determine the best option based on your financial situation.

What documents are needed for an Oklahoma mortgage application?

You will need 2 years of W2s, your most recent 30-day pay stub with year-to-date information, account statements for the past 30 days, names and addresses of your employers for the past two years, a letter explaining any gaps in employment, and other information as required by underwriters.